
RBI rejects all bids at Treasury bill auction as short-term yields surge
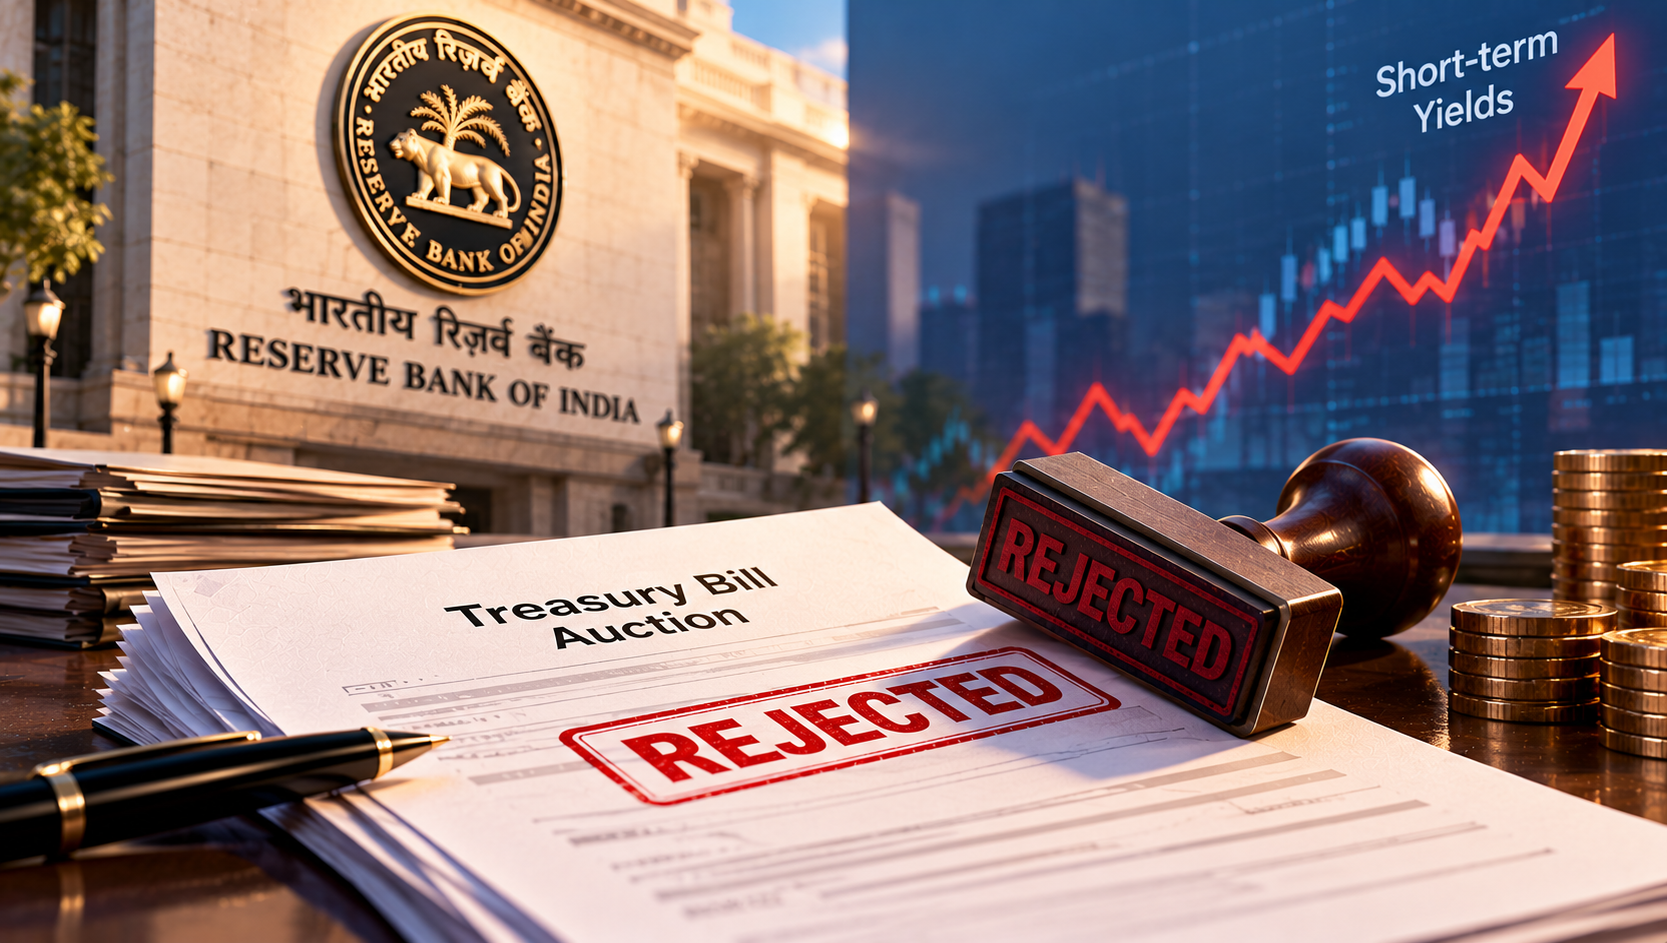
The Reserve Bank of India (RBI) on Wednesday refused to accept any bids at the government’s treasury bill (T-bill) auction, which market participants said reflected the central bank’s unease with the sharp increase in short-term borrowing costs.The yield on the benchmark 10-year government security closed at 7.44 per cent, up from 7.39 per cent in the previous session and the highest level since November 4, 2022.The RBI had last turned away bids in June, when it cancelled auctions for the 182-day and 364-day T-bills.
Earlier, at the end of March, it had rejected bids for all three standard T-bill maturities.For the latest auction, the government had targeted raising ₹23,000 crore via 91-day, 182-day and 364-day T-bills. According to traders, the yields demanded by investors were likely above the RBI’s comfort zone. Government securities, which were already under pressure from higher crude oil prices and rising US Treasury yields, weakened further after the auction outcome.A dealer at a primary dealership said the 10-year benchmark yield could now move towards 7.50 per cent. He pointed out that Brent crude around $112 per barrel and higher US yields were weighing on sentiment, which turned negative again once the auction result was made public.T-bill cutoff yields have climbed sharply over the last five weeks.
Between September 9 and October 14, yields on 91-day, 182-day and 364-day bills rose by 64 basis points, 83 basis points and 69 basis points, respectively.At the previous week’s auction, the government had raised money at 5.73 per cent for 91-day bills, 6.29 per cent for 182-day bills and 6.49 per cent for 364-day bills.The spread between the 364-day T-bill yield and the RBI’s policy repo rate widened to 99 basis points last week, the highest in four years, underscoring the rise in short-term funding costs.The RBI has adopted a clearly hawkish stance. It increased the repo rate to 5.50 per cent this month and shifted its policy stance to calibrated tightening, indicating room for further hikes.
Market expectations of a 50 basis point rate increase in December are building, and the 10-year benchmark yield has already climbed about 20 basis points since the policy announcement.The liquidity cushion that had supported the bond market for much of the year has thinned considerably. RBI data showed that net liquidity in the banking system was in surplus by about ₹48,303 crore on Tuesday.As a result, the RBI’s overnight variable rate repo (VRR) operation drew strong interest, with bids of ₹93,241 crore against a notified amount of ₹50,000 crore.
The weighted average call rate (WACR), the operating target for monetary policy, ended at 5.64 per cent on Wednesday, close to the marginal standing facility (MSF) rate, compared with 5.66 per cent a day earlier. On Monday, the RBI had conducted a ₹1 trillion VRR auction, its first such operation in three months.A dealer at a state-owned bank said liquidity has almost dried up, keeping overnight rates elevated, and added that upcoming tax outflows will add further pressure. According to him, the RBI wants overnight rates to stay aligned with the repo rate, which explains these short-term liquidity injections.
The liquidity backdrop has reversed sharply. Since August 6, after its previous VRR auction on July 29, the RBI had largely been absorbing surplus liquidity, which had swelled due to Foreign Currency Non-Resident Bank [FCNR(B)] deposit swap operations with the central bank.From October 16, the daily cash reserve requirement has also been tightened. Average daily net absorption under the liquidity adjustment facility rose from ₹1.2 trillion in July to ₹5.8 trillion in August. As recently as October 12, the RBI absorbed a net ₹3.36 trillion, when the call rate was at 5.41 per cent.The RBI has announced another overnight VRR auction of ₹50,000 crore to be held on Thursday.
Source: bsindia
Related Posts
RBI MPC Minutes Hint at Rate Hike or Pause as Two Members Oppose Policy Shift
RBI MPC minutes signal a higher-for-longer rate environment, making debt allocation and duration choices critical for MFDs advising clients amid persistent inflation risks.
SEBI issues warnings to over 200 foreign funds following post-Hindenburg scrutiny
Sebi’s post-Hindenburg scrutiny has tightened FPI disclosure and KYC norms, but its use of warnings over penalties reduces disruption risk for foreign capital flows into Indian markets.
SAT reserves order in Jane Street case over access to SEBI documents
SAT’s pending decision in the Jane Street–SEBI dispute underscores the regulator’s aggressive stance on alleged index manipulation, a key signal for MFDs tracking market integrity and regulatory risk.

1 Finance gets in-principle approval for India’s first MF Lite AMC licence
SEBI’s in-principle MF Lite approval for 1 Finance signals growing regulatory support for low-cost passive mutual fund offerings that MFDs may soon distribute.

AIF boom exposes conflict-of-interest risks in in-house distribution, pushing SEBI toward greater transparency on commissions.
Growing AIF scale and SEBI’s tightening scrutiny of commissions and conflicts mean MFDs must be extra transparent on fees and product selection when dealing with high-net-worth clients in alternatives.
RBI MPC Minutes Hint at Rate Hike or Pause as Two Members Oppose Policy Shift
RBI MPC minutes signal a higher-for-longer rate environment, making debt allocation and duration choices critical for MFDs advising clients amid persistent inflation risks.
SEBI issues warnings to over 200 foreign funds following post-Hindenburg scrutiny
Sebi’s post-Hindenburg scrutiny has tightened FPI disclosure and KYC norms, but its use of warnings over penalties reduces disruption risk for foreign capital flows into Indian markets.
SAT reserves order in Jane Street case over access to SEBI documents
SAT’s pending decision in the Jane Street–SEBI dispute underscores the regulator’s aggressive stance on alleged index manipulation, a key signal for MFDs tracking market integrity and regulatory risk.
1 Finance gets in-principle approval for India’s first MF Lite AMC licence
SEBI’s in-principle MF Lite approval for 1 Finance signals growing regulatory support for low-cost passive mutual fund offerings that MFDs may soon distribute.
AIF boom exposes conflict-of-interest risks in in-house distribution, pushing SEBI toward greater transparency on commissions.
Growing AIF scale and SEBI’s tightening scrutiny of commissions and conflicts mean MFDs must be extra transparent on fees and product selection when dealing with high-net-worth clients in alternatives.